We've added three new tools to Model Portfolios to help you manage allocations and work with holdings across different periods:
- Proxies let you use another security to represent a holding before it began trading, so you can evaluate your strategy over a longer period without changing your intended allocations.
- Apply drifted weights populates a custom allocation period with the weights your portfolio actually held on that date, so you can make one-for-one allocation substitutions without rebalancing the entire model.
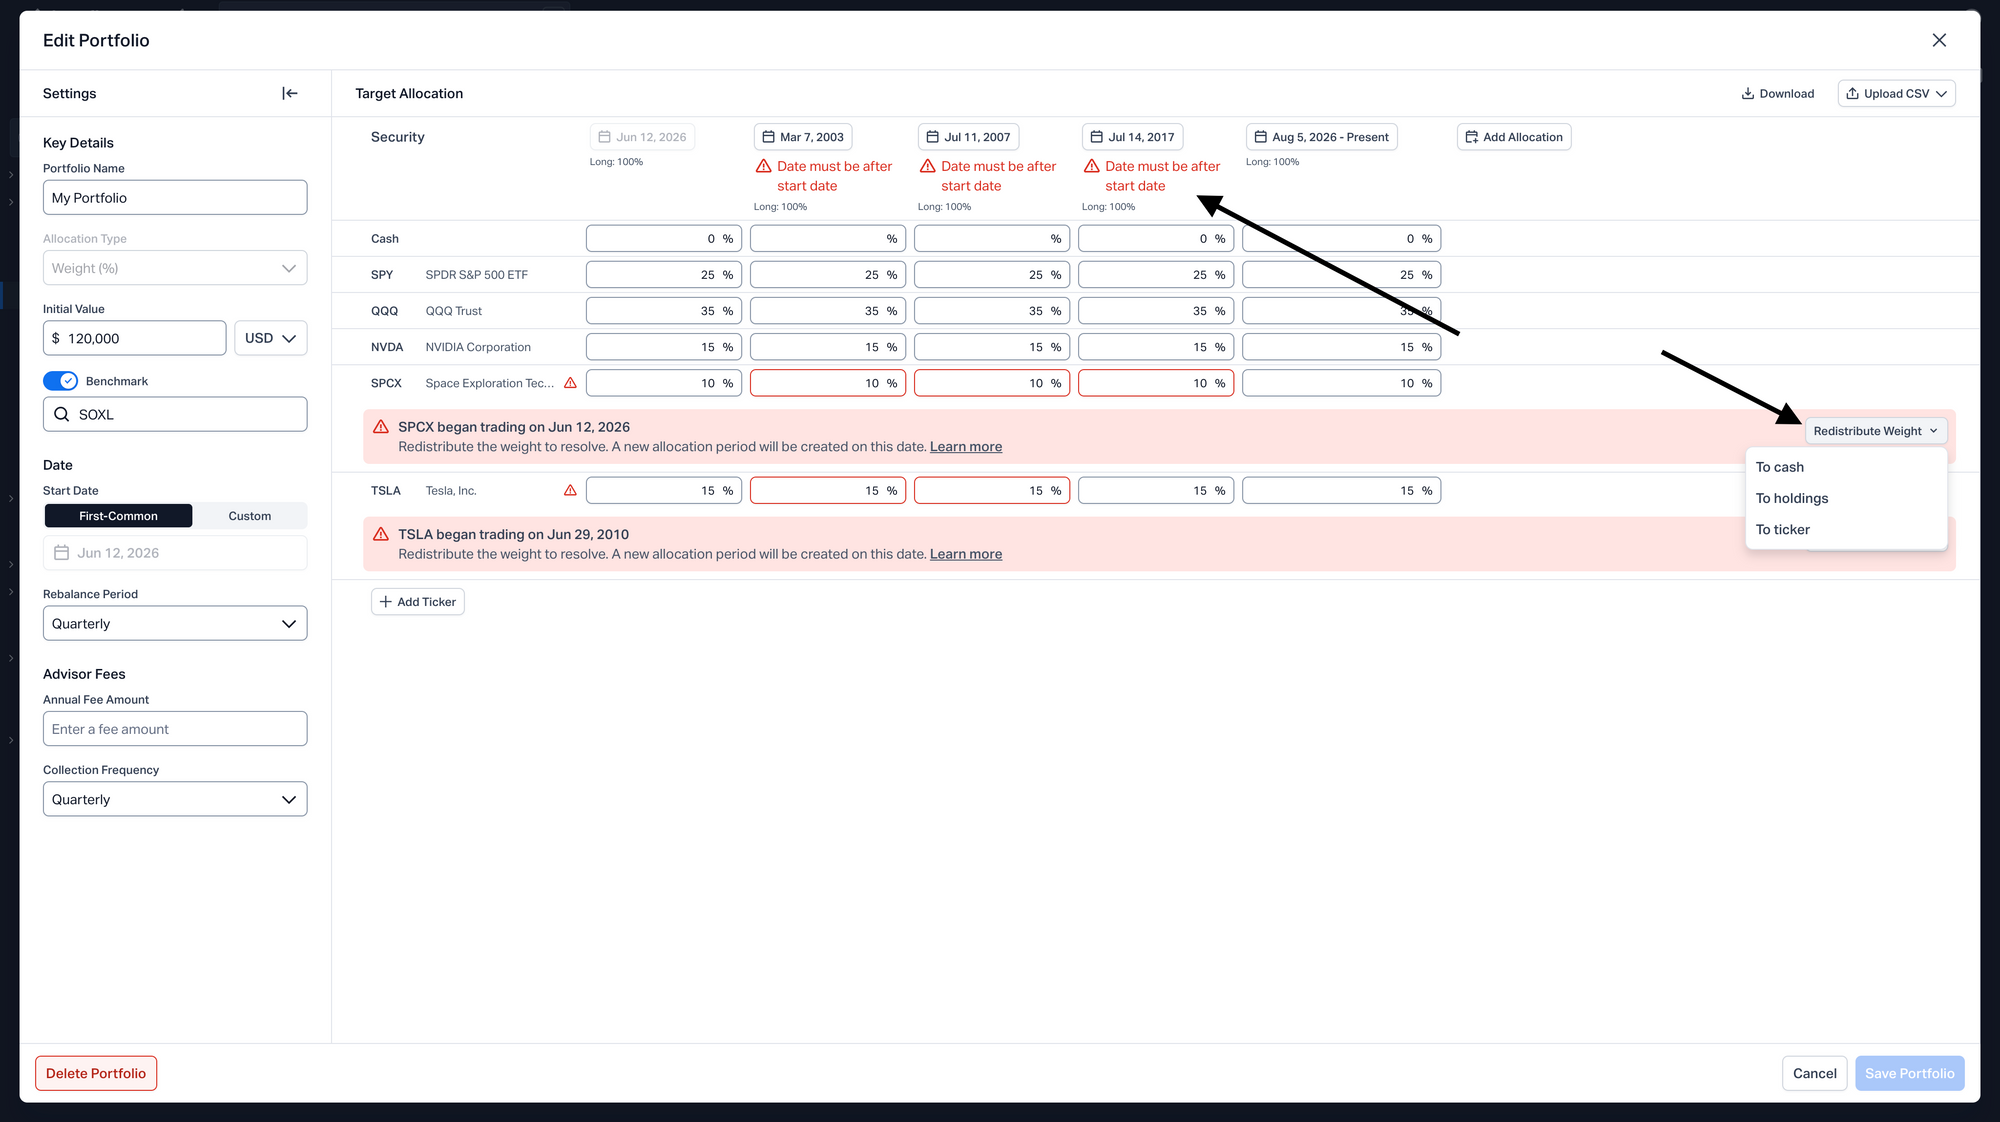
- Redistribute Weight handles errors for holdings that weren't trading on a selected allocation date, allowing you to redistribute their weight to cash, across all other holdings, or to a single security.
Proxies for historical allocations
If your model includes a recently issued security, you can use an older security with a longer trading history as its proxy. The model uses the proxy's returns at the holding's intended weight until the actual holding begins trading.
An example of when this would be useful is if your model uses a thematic ETF that was issued two years ago. In order to extend the history of the model, you may use an older ETF which covers the same theme as the proxy.
Proxies are available when Start Date is set to Custom in the Edit Portfolio window.
Assign a proxy
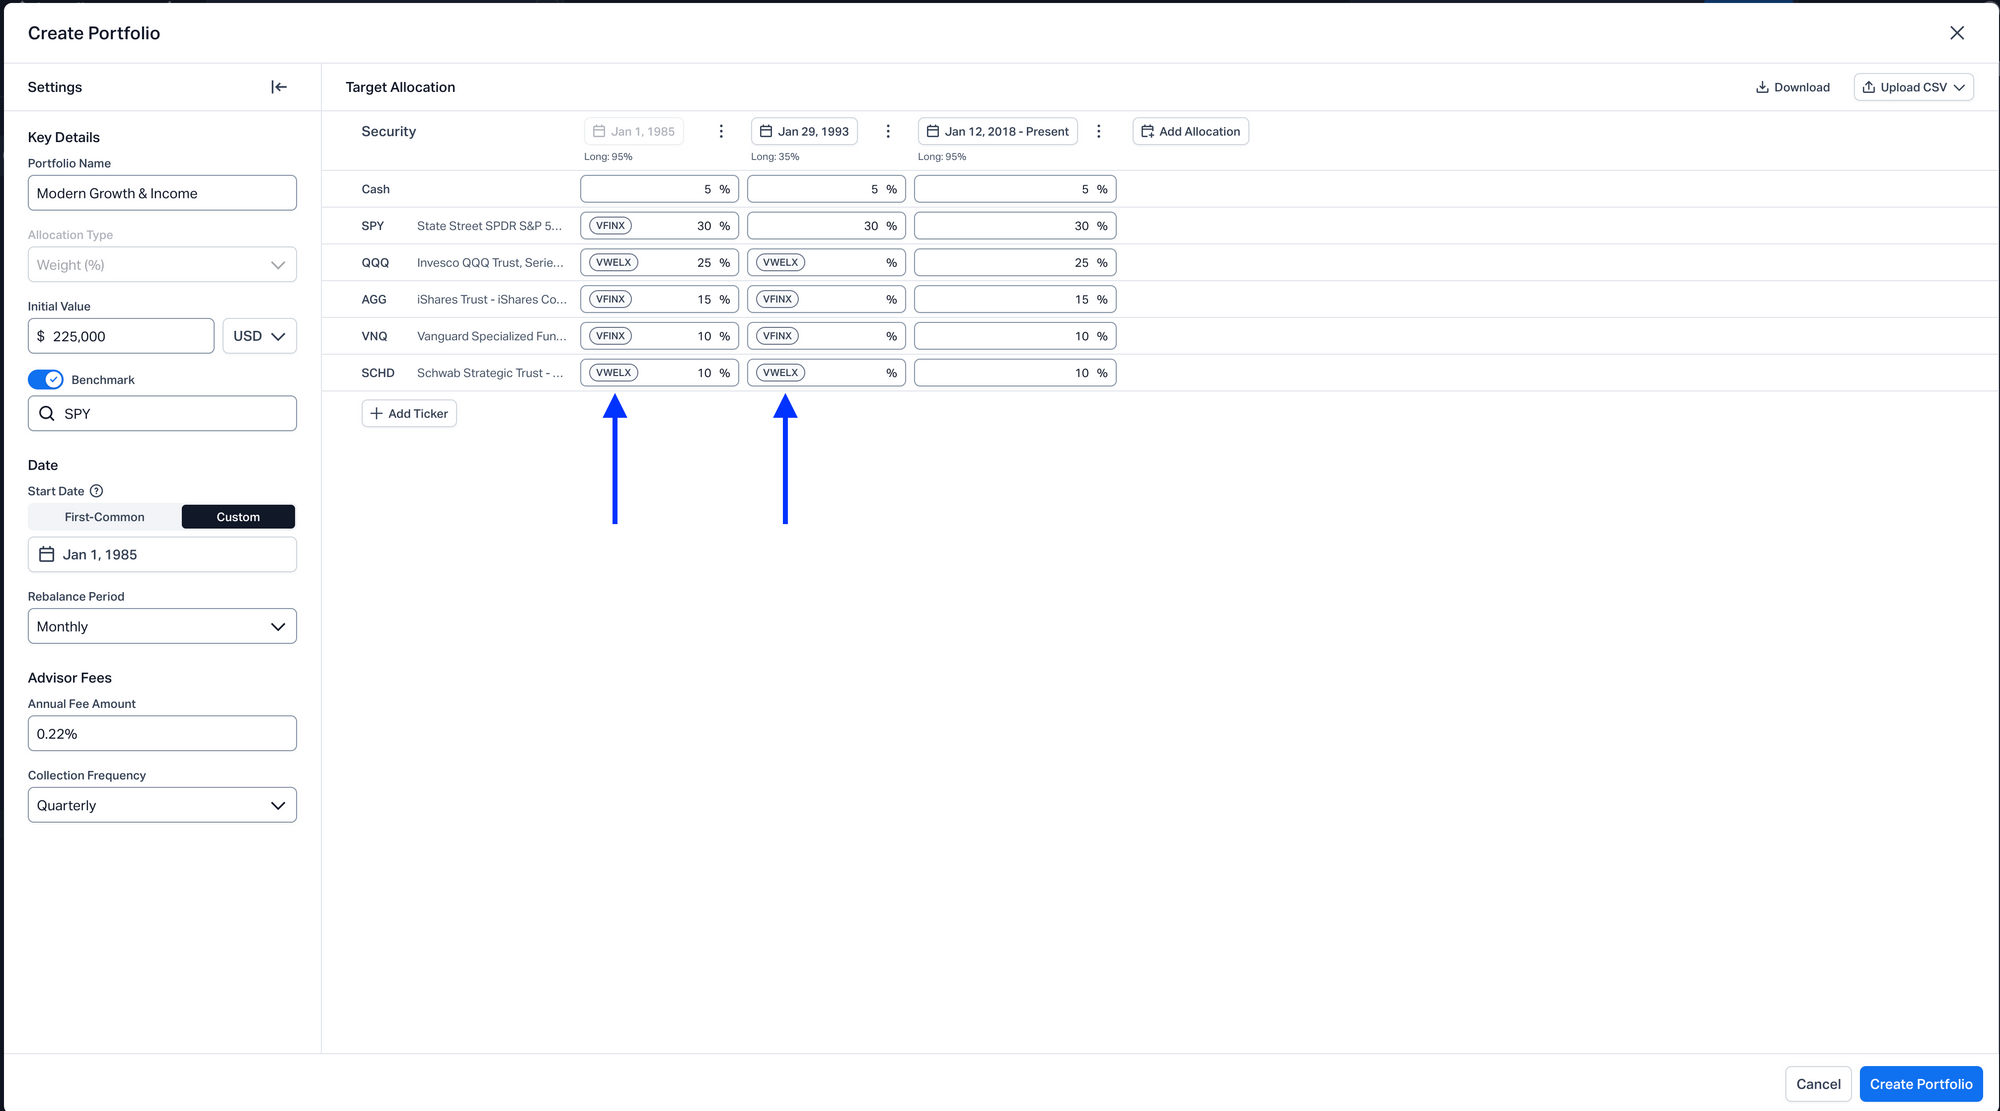
- Open Edit Portfolio, set Start Date to Custom in the Settings panel, and choose a date.
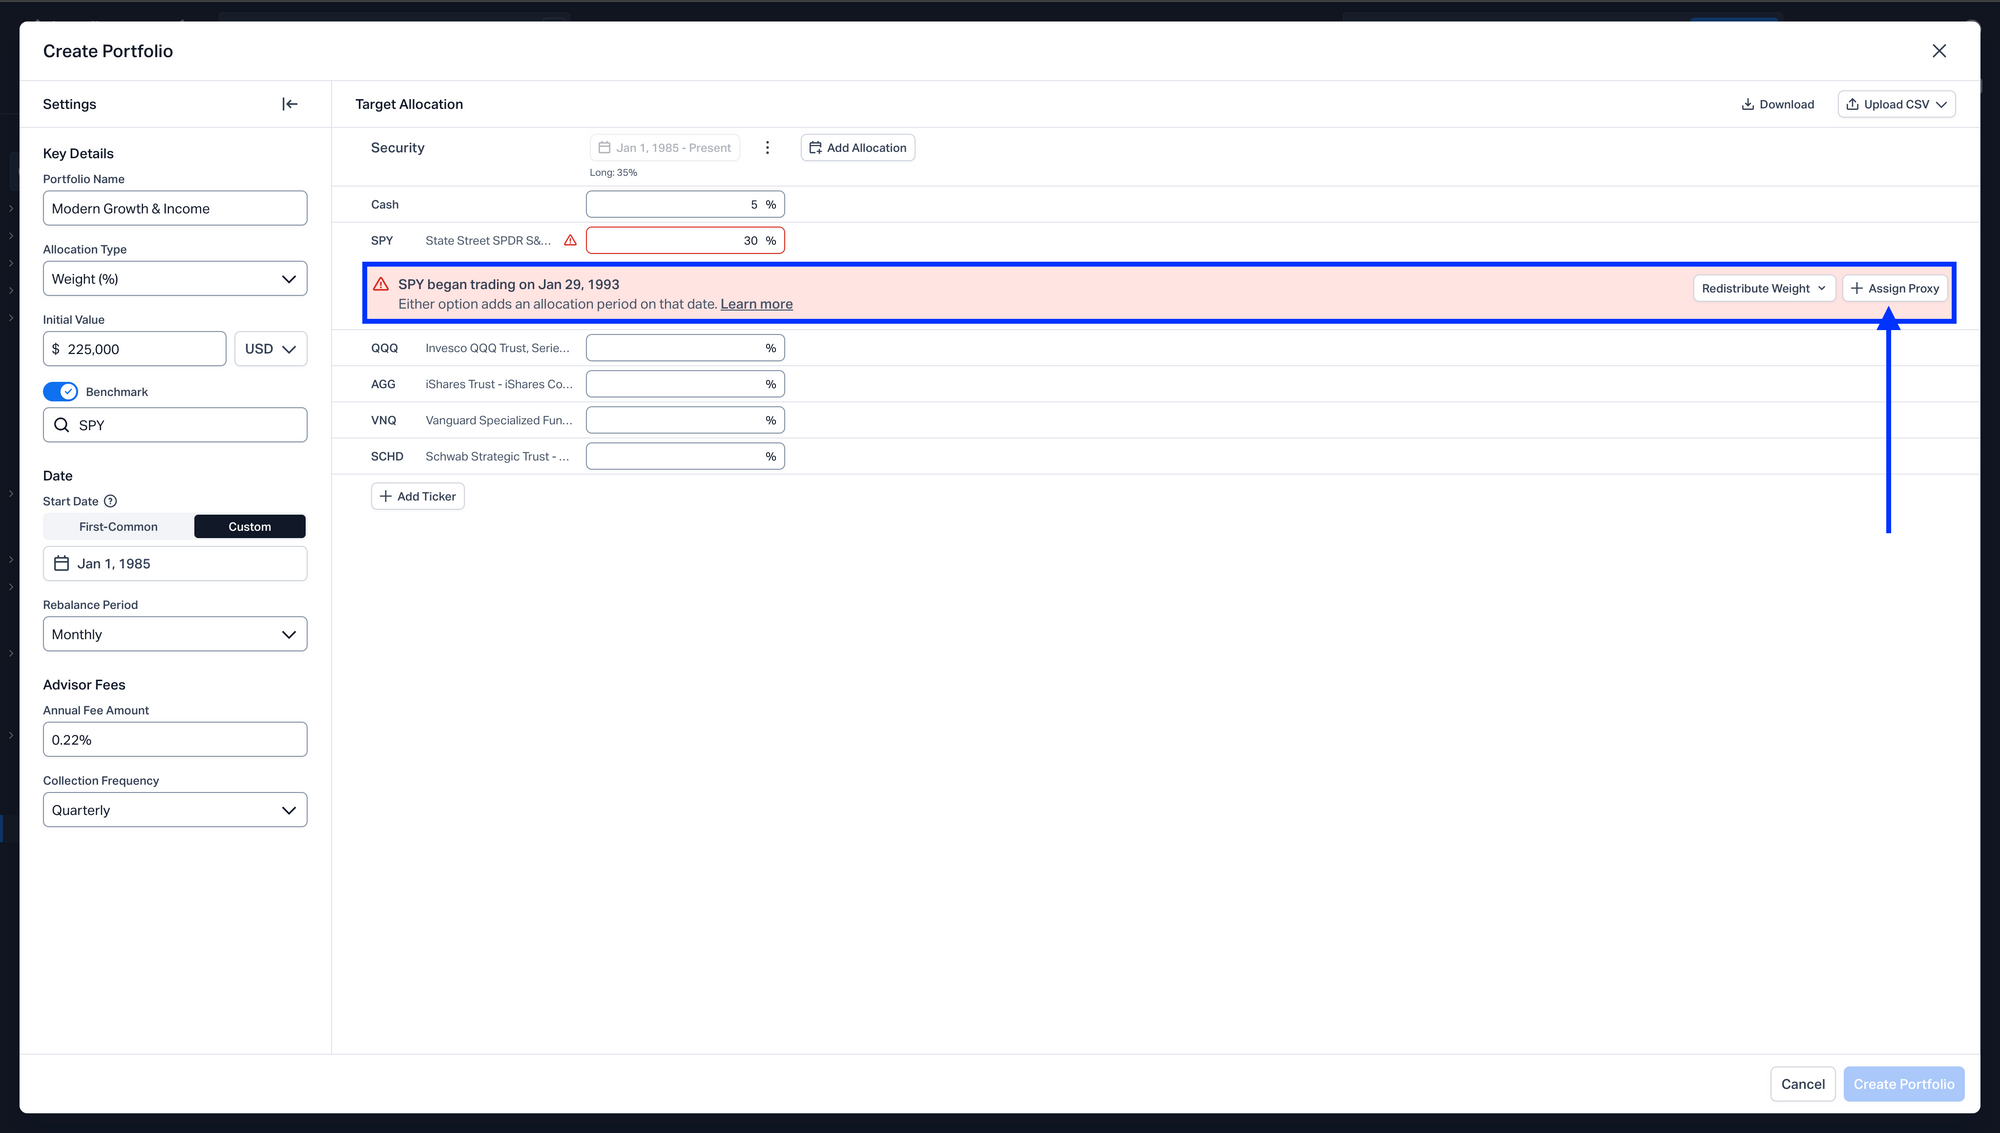
- For holdings that began trading after your selected date, click Assign Proxy.
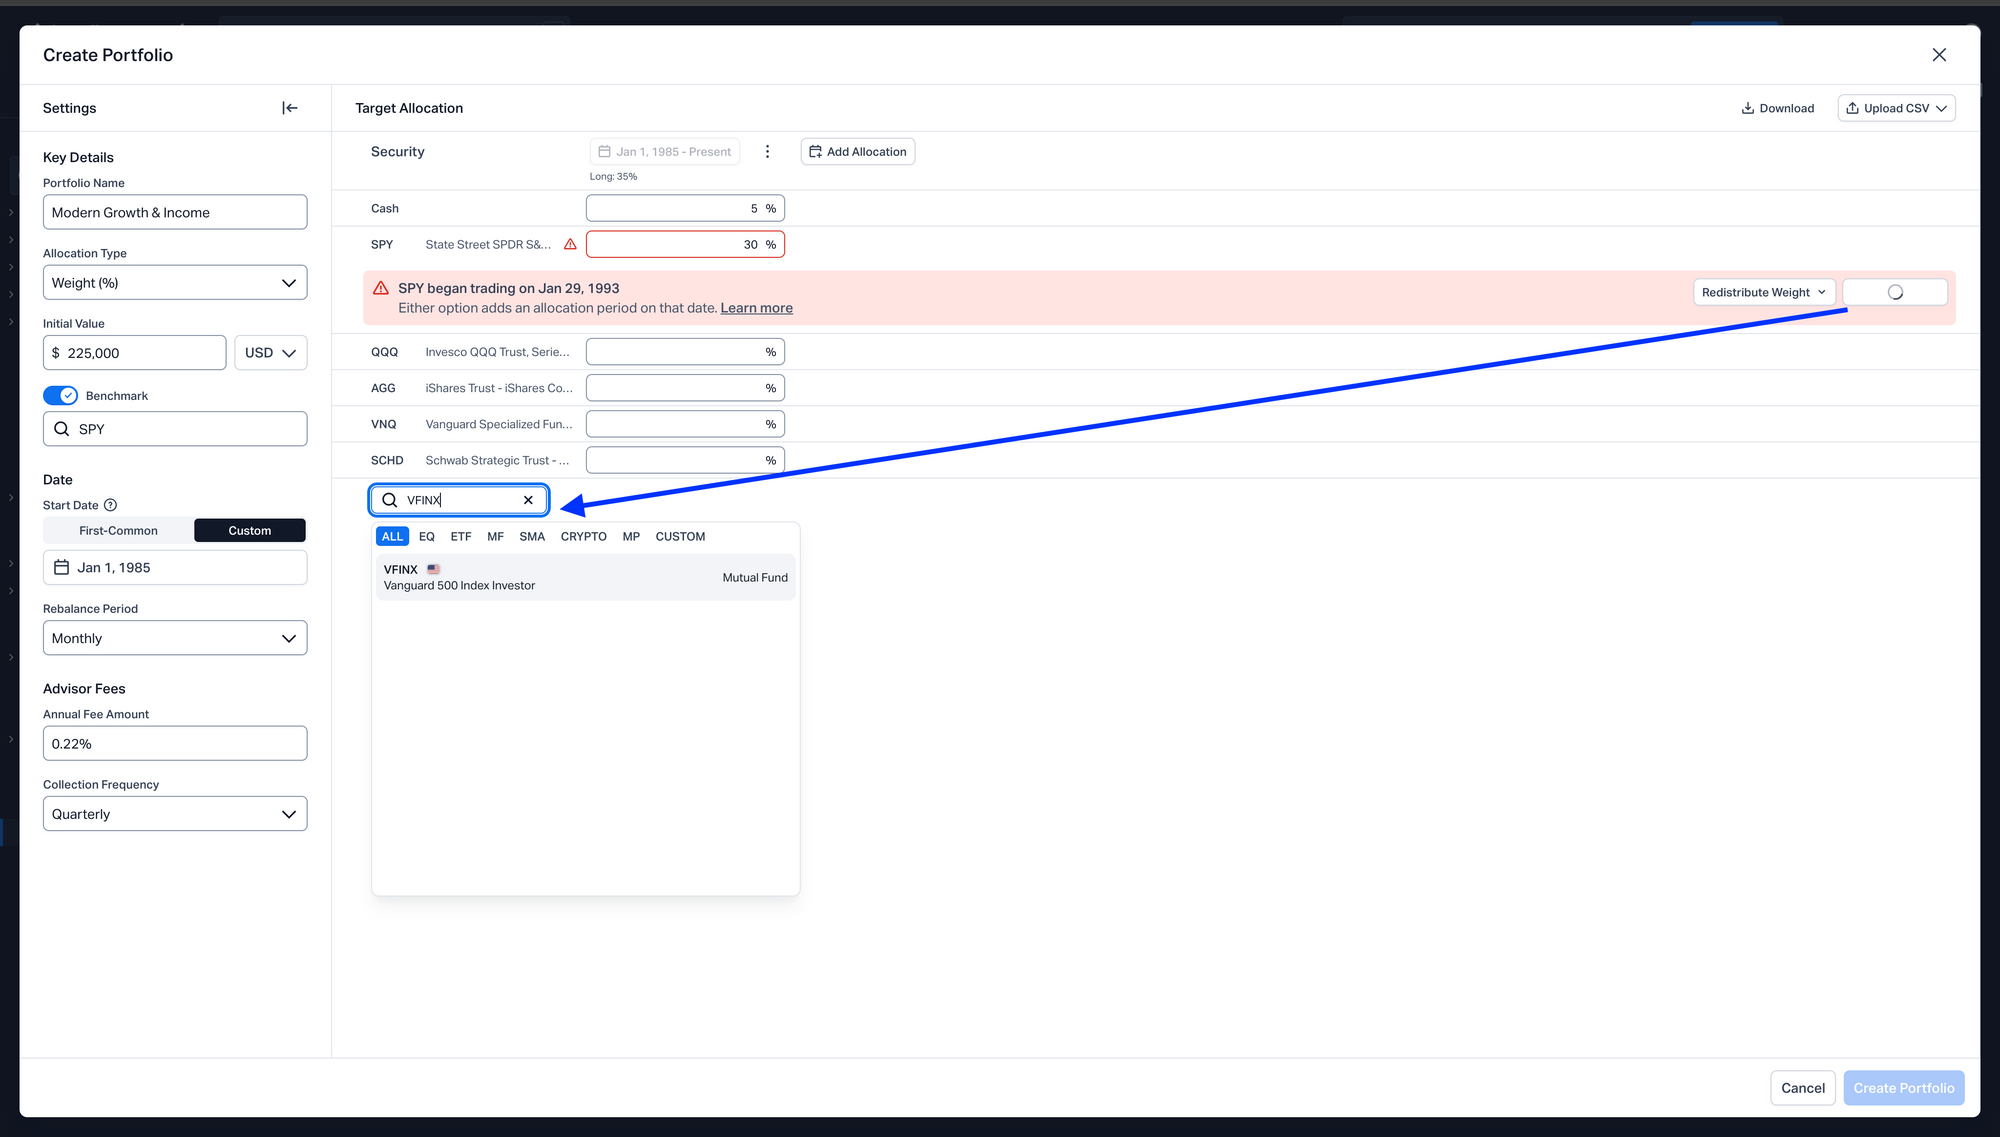
SPY is assigned as the default proxy, and a new allocation period is created on the holding's first trading date using your entered weights. You can’t save the model while a proxy doesn’t cover its start date.
The proxy applies to every allocation period before the holding’s first trading date, including any you add later.
Change or remove a proxy
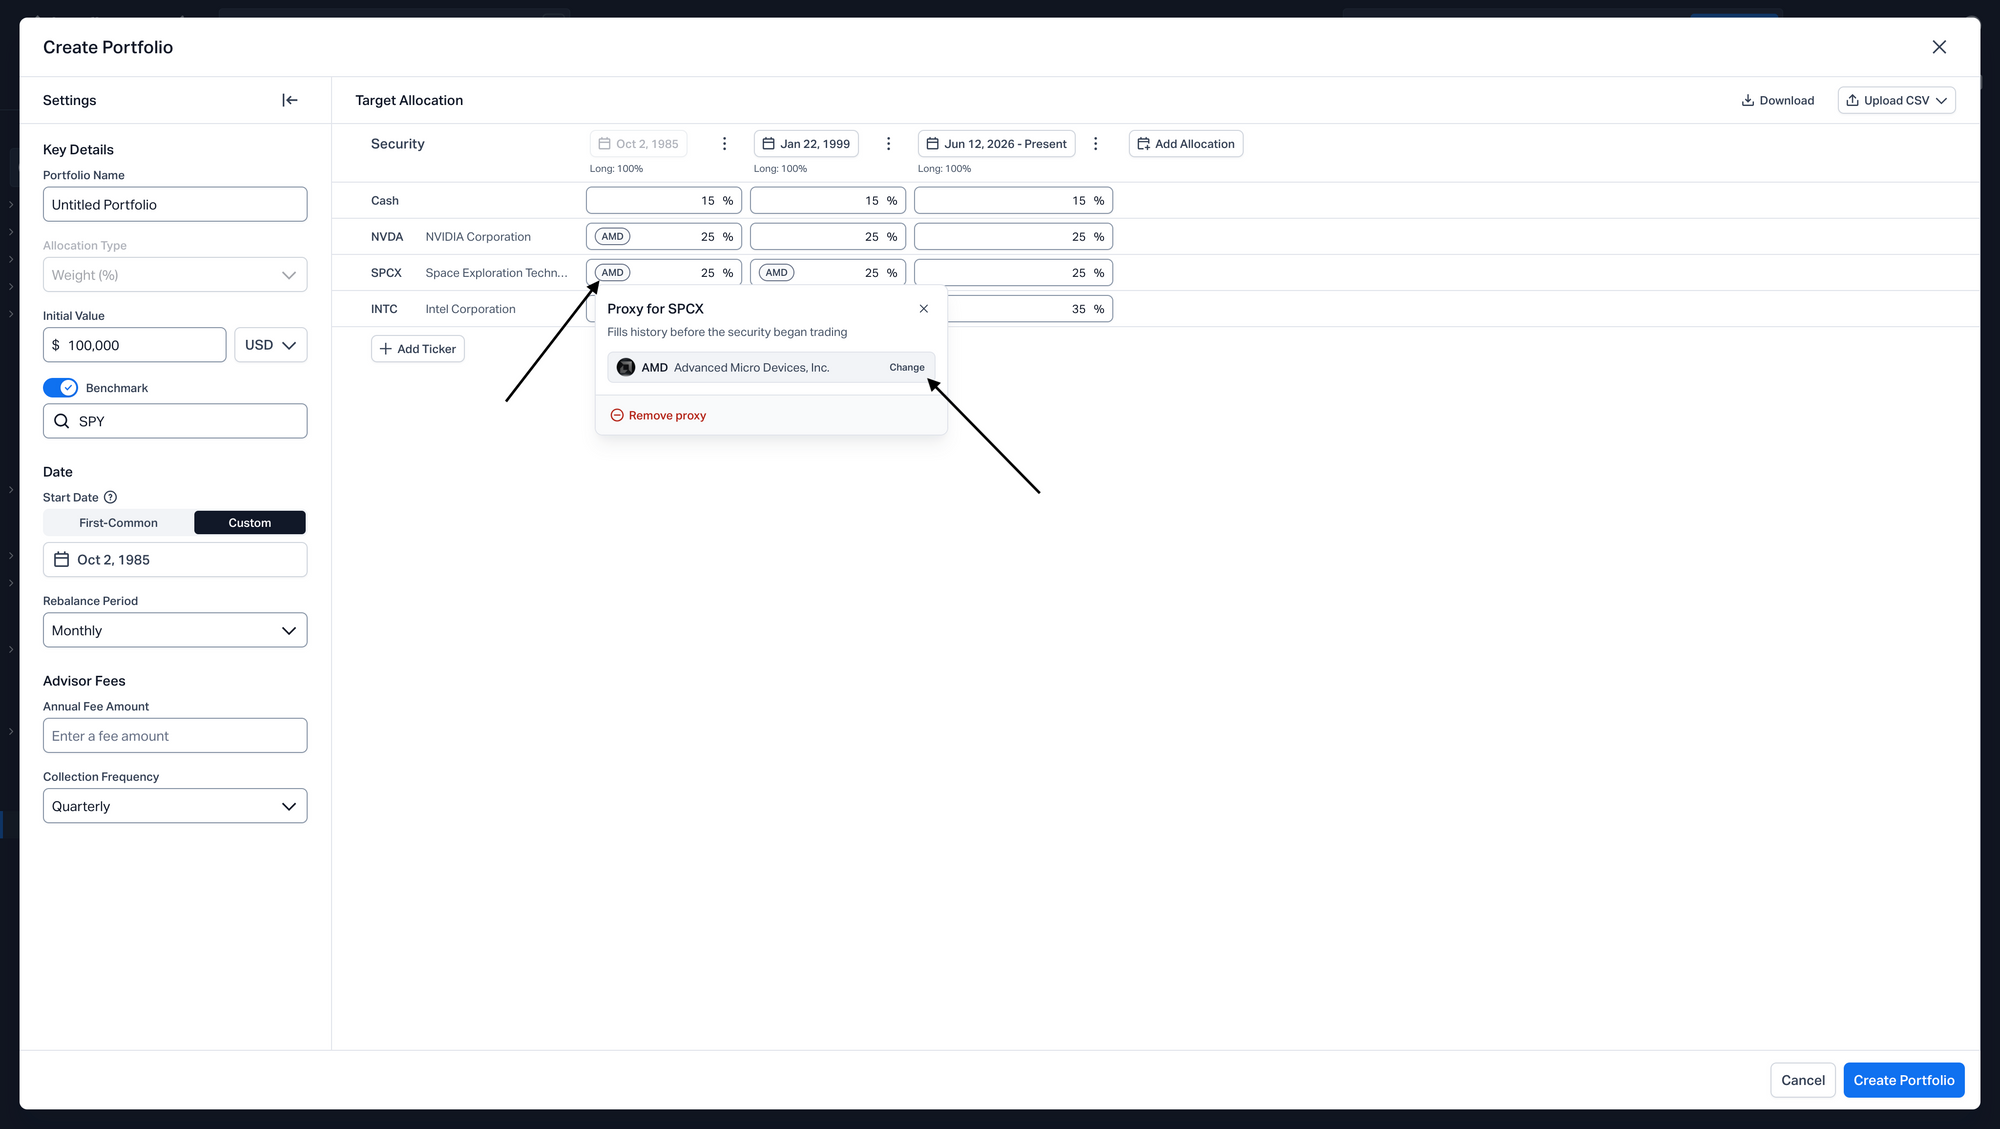
Click the proxy chip in any weight cell to open Proxy for [ticker].
- Change the proxy: Click Change, search by name or ticker, and select a security.
- Remove the proxy: Click Remove proxy. The trading-date conflict returns and must be resolved another way, such as Redistribute Weight, before you can save. The allocation period created on the holding’s first trading date remains.
Changes to a proxy apply to all periods where it's used. Any replacement must have trading history going back to the model’s start date. If it doesn’t, Koyfin flags it and the change isn’t applied. Select a different security instead.
Supported proxy types
You can use stocks, ETFs, mutual funds, SMAs, cryptocurrencies, model portfolios, and custom data series as proxies. Client portfolios are not supported.
Proxies also work with short positions and securities already held in the model. If the proxy is an existing holding, each position remains separate in the allocation table.
If a model portfolio or custom data series used as a proxy is deleted or is no longer shared with you, SPY automatically replaces it.
How proxies affect model results
- Attribution and Contribution: The proxied weight is reported under the proxy. If the model also holds that security directly, the positions appear as one combined position.
- Apply drifted weights: If the model holds both the proxy and the security it represents, the split between them stays as you set it, since both are following the same security’s returns.
- Exposure: Calculations reflect the model's actual holdings, not their proxies.
- CSV exports: The proxy appears as the holding for the periods it covers. Importing the CSV creates a model that holds the proxy directly, without preserving the proxy assignment.
Switch to First-Common
First-Common starts the model on the earliest date when all holdings in the initial allocation were trading, so those holdings don’t need proxies.
To switch, change Start Date to First-Common in Edit Portfolio and confirm the change.
This removes all proxies and allocation periods automatically created to resolve trading-date conflicts. Changes won't affect your saved model until you click Save.
Apply drifted weights to an allocation period
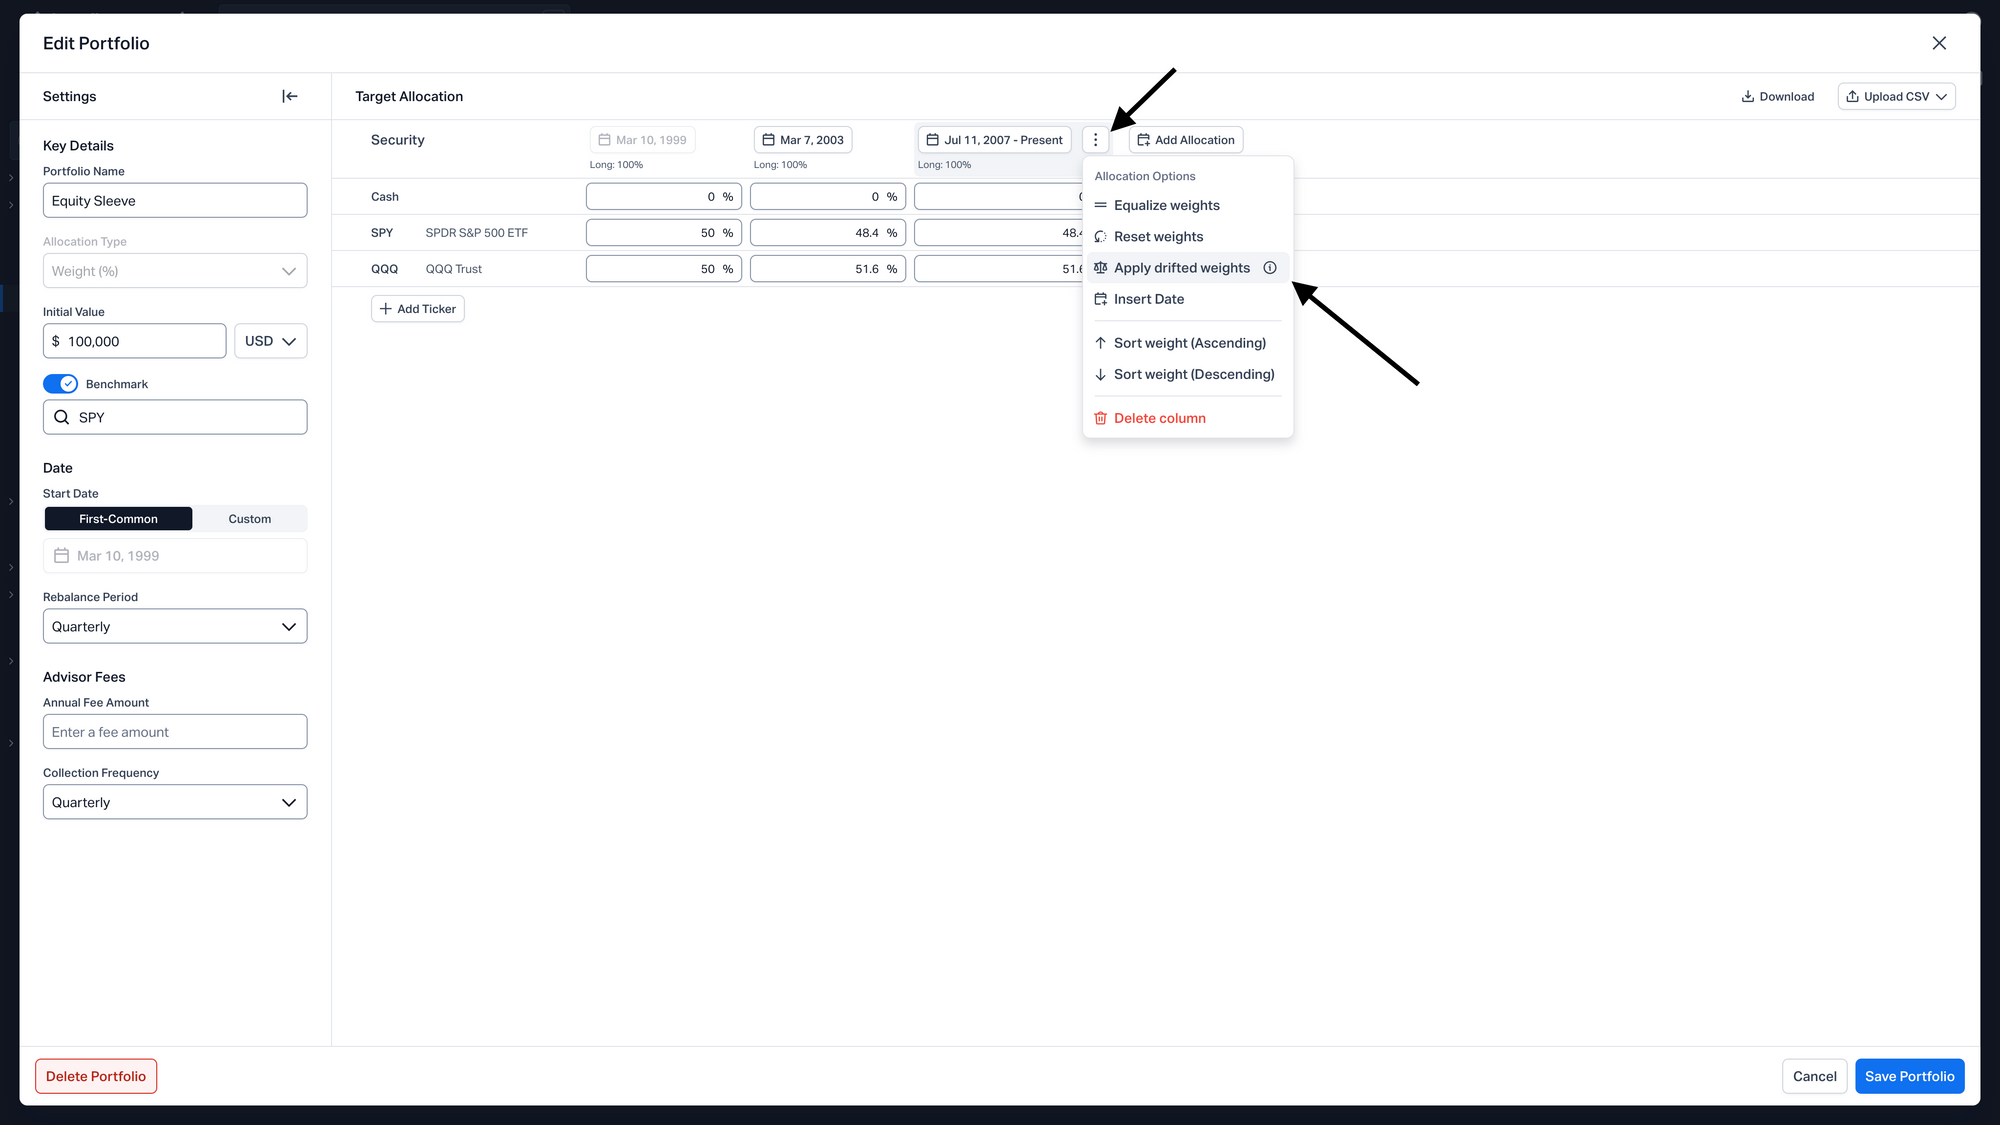
- In the Edit Portfolio window, hover over the column header of the allocation period you want to update and click the three-dot menu next to the date.
- Under Allocation Options, select Apply drifted weights.
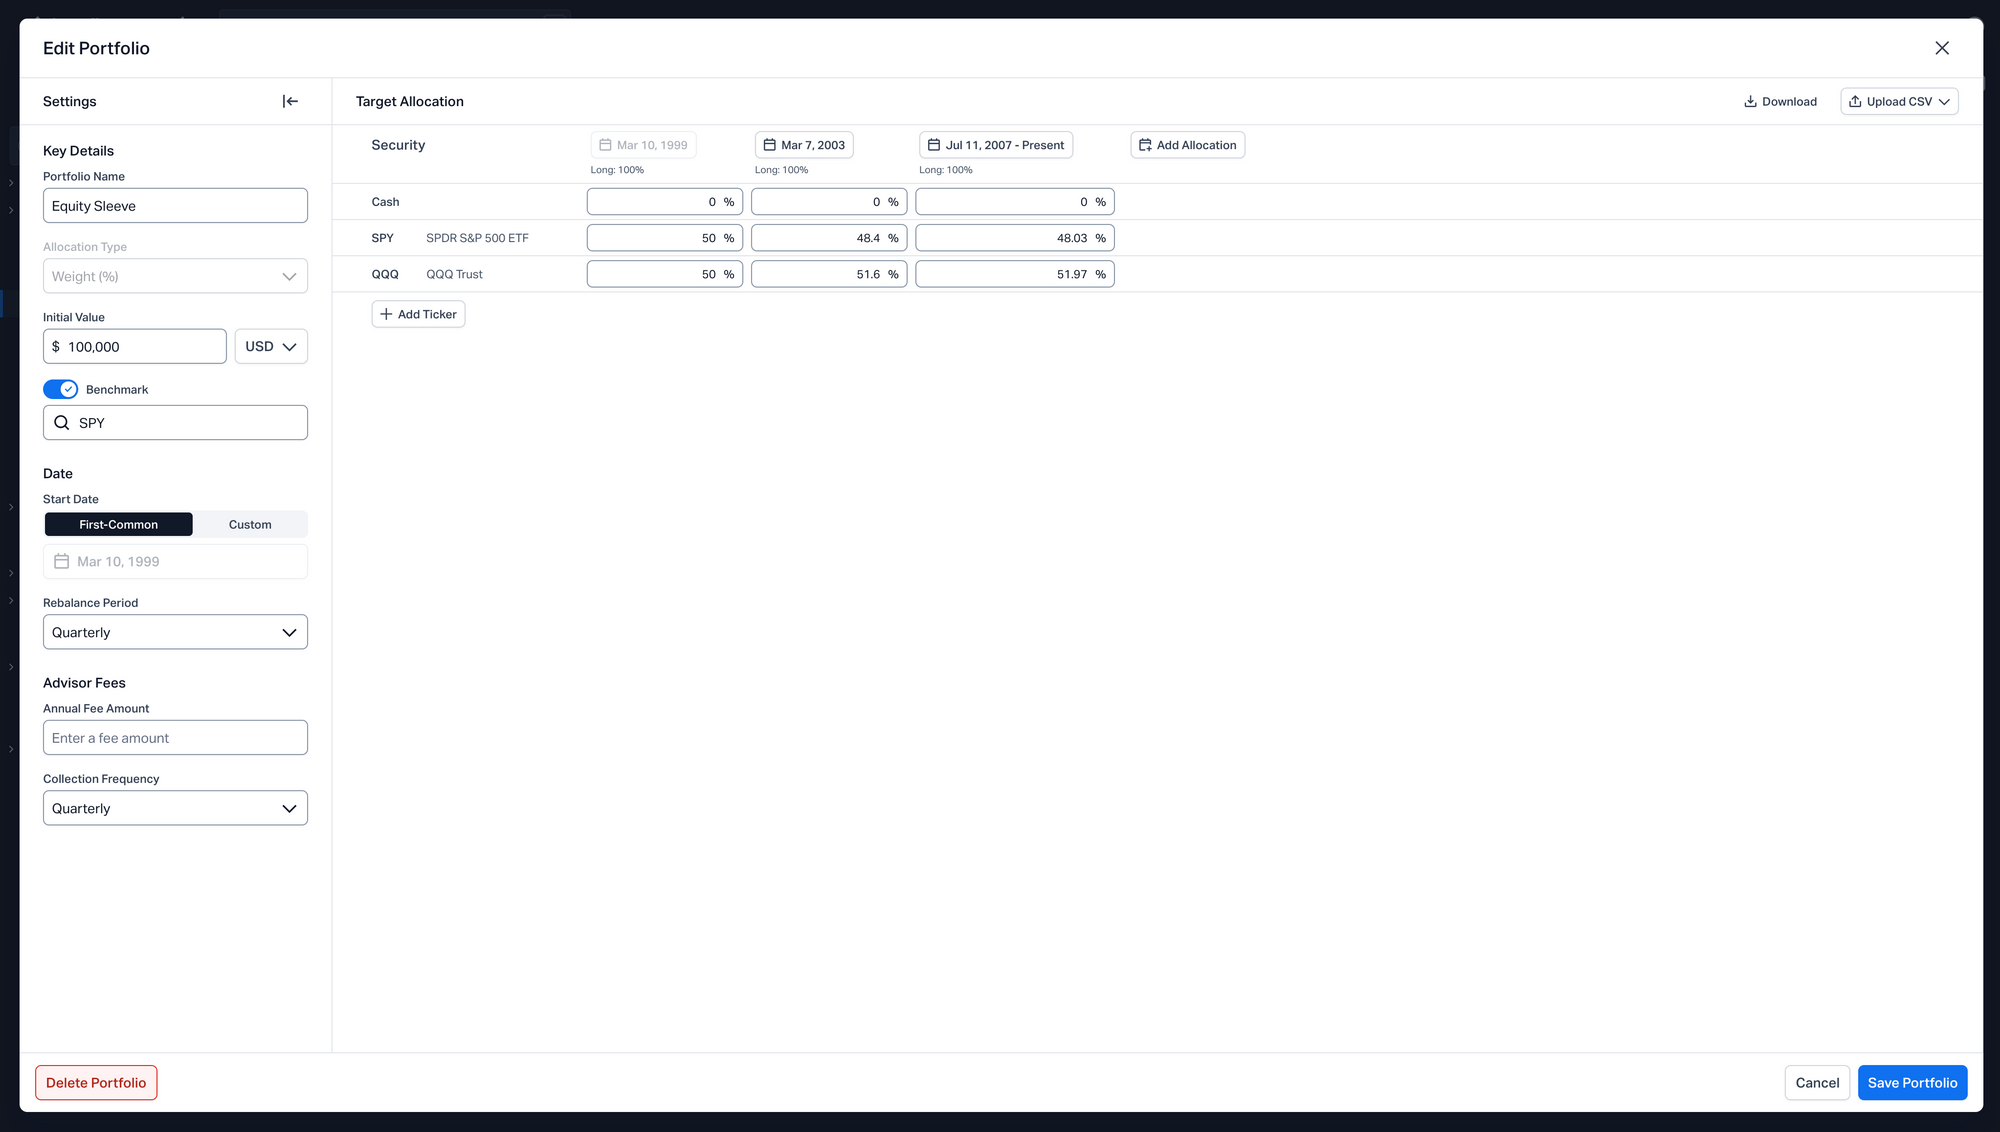
The period updates with the portfolio's drifted weights, so you can adjust only the positions you're buying or selling. Other allocation periods are not affected.
Apply drifted weights is available on every allocation period after the first, once all conflicts in the model are resolved.
The calculated weights account for the model's rebalance period and any unsaved edits. If you apply drifted weights to several periods in sequence, each calculation uses the newly drifted weights from the period before it. The new weights populate straight away, but aren’t saved to the model until you click Save Portfolio.
Resolve holdings that weren't trading on the selected date
A conflict occurs when a holding has a weight above 0% in an allocation period when it wasn't trading. The affected weight is highlighted, with options to resolve the conflict.
The available options depend on when the security traded:
- Began trading on [date]: The security started trading after the allocation period, which can happen when using a Custom start date. You can assign a proxy or redistribute its weight.
- Stopped trading on [date]: The security stopped trading during the model's history. Use Redistribute Weight to reallocate its weight.
- Stopped trading on [date], before this portfolio starts: The security was already inactive before the model began. Use Delete Holding to remove it.
You must resolve all conflicts before saving the model.
Securities that have stopped trading are also flagged in existing models when you next edit them. If a holding both started and stopped trading during the model's history, the second conflict appears after you resolve the first.
You can also resolve conflicts by setting the affected holding's weight to 0%, changing the allocation period's date to one when the security was trading, or switching to First-Common in Settings. First-Common starts the model on the earliest date when all holdings in the initial allocation were trading, so those holdings don’t need proxies. A security added to a later period can still begin trading after that date, and would need resolving separately.
Redistribute a holding's weight
Click Redistribute Weight below the affected holding and choose where to move its weight:
- To cash: Adds the weight to the model's cash allocation.
- To holdings: Distributes the weight proportionally across the period's other long holdings, including cash if it has a positive weight.
- To ticker: Lets you select a replacement security to take on the weight in the new allocation period.
Redistributing weight creates a new allocation period on the security’s first or last trading date. If a period already exists on that date, Koyfin updates it instead of creating another, and any periods in between remain unchanged.
- If the security began trading later: The earlier period is rebalanced without that security. The new period starts on its first trading date with your intended allocation, including the security at its assigned weight.
- If the security stopped trading: The earlier period remains unchanged. The new period starts on the security’s last trading date, with its weight reduced to 0% and redistributed as selected.